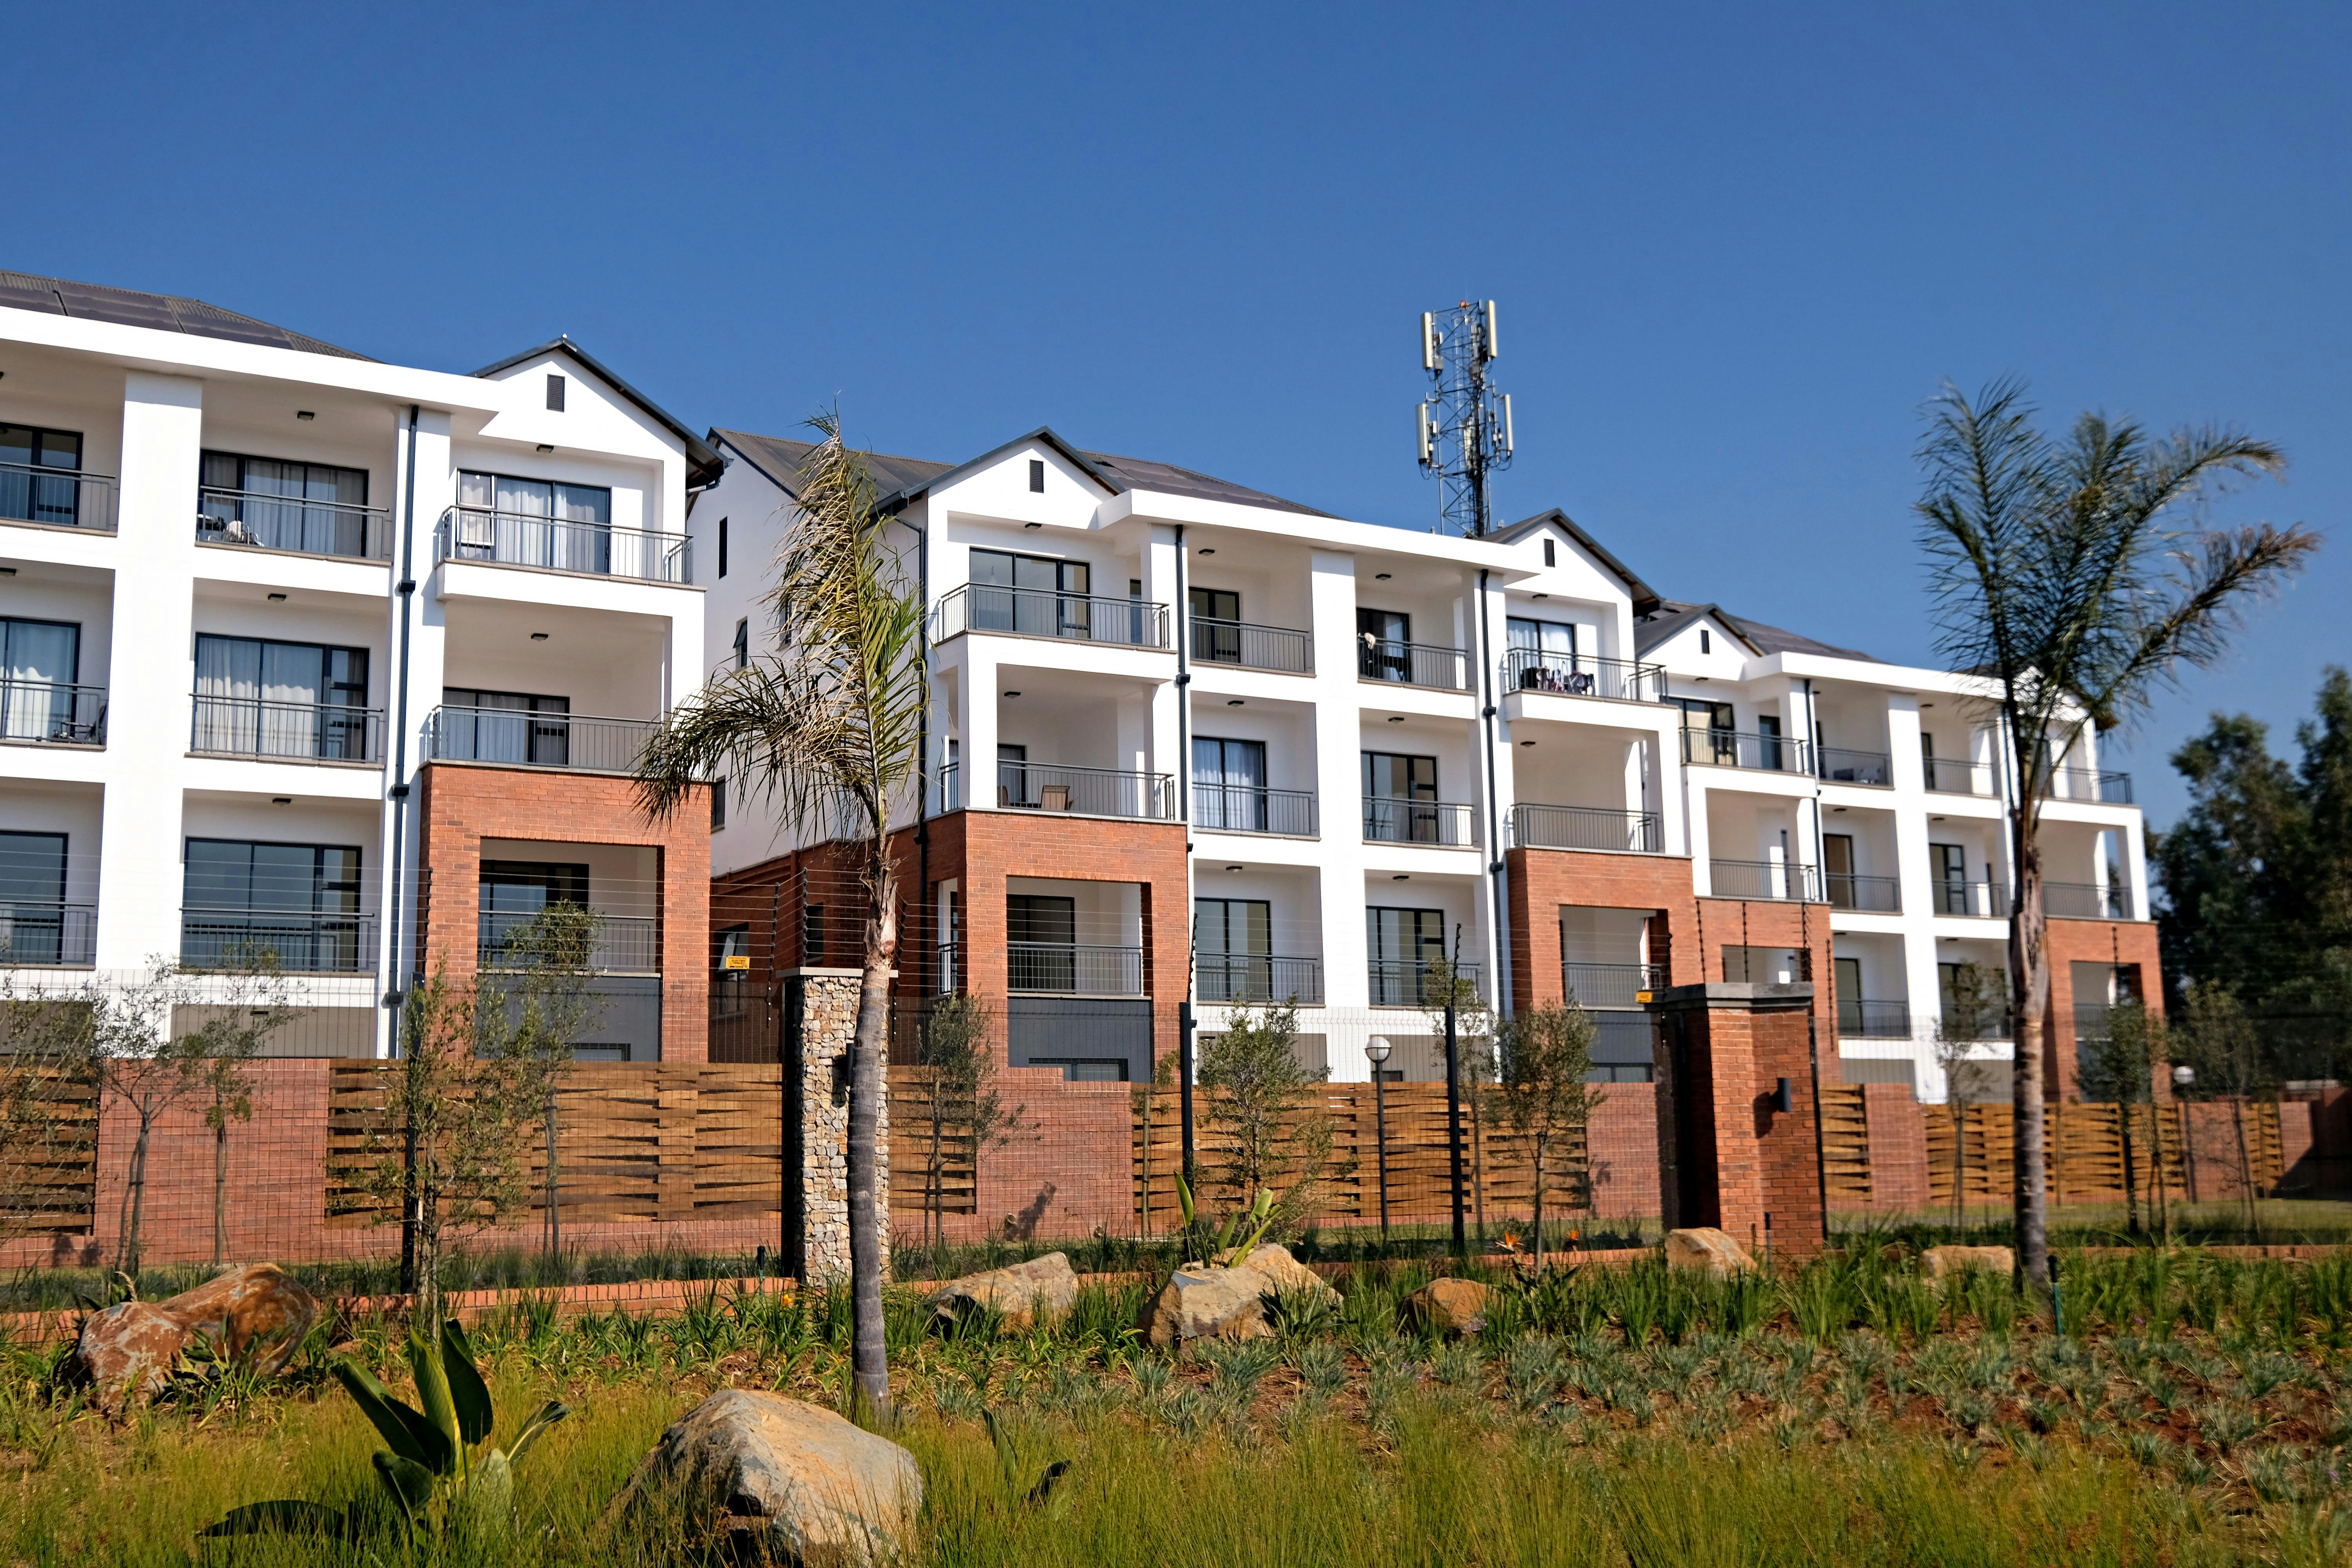

Owning a strata property comes with responsibilities that aren’t always obvious at first. You have your own lot, but you also share parts of the building with other owners. The roof, foyer, external walls, lifts, gardens, and other common areas all need attention when something goes wrong. Insurance is a big part of that picture.
Strata Insurance Australia is generally arranged for the building and common property, rather than the personal belongings inside an individual lot. The owners corporation is usually responsible for arranging the required cover. Exactly what must be insured depends on the state or territory, so owners should check the rules that apply to their property.
Start With the Building
The first question is fairly simple: what happens if the building suffers serious damage? Strata building insurance is intended to provide cover for insured damage to the property. Depending on the policy, this may extend to the building structure, fixtures, common areas, and other items that fall within the relevant definition of the insured property.
That distinction matters because strata insurance isn’t the same thing as a standard home contents policy. The policy is concerned with the property and shared areas that the owners corporation is responsible for.
The exact boundaries can depend on the building, the policy wording, and local legislation. Owners shouldn’t assume that everything physically attached to the property falls under the same cover.
The Rules Depend on Where the Property Is
Australia doesn’t have one single set of strata insurance rules. Each state and territory has its own legislation, which means the insurance requirements for a strata scheme in Sydney may differ from those for a property in Melbourne, Brisbane, or Perth.
That makes local advice important. A policy shouldn’t be selected on the assumption that the same requirements apply everywhere.
How Much Building Cover Is Enough?
This is where the property’s value can cause confusion. The market price of a building isn’t necessarily what it would cost to rebuild. Location can push a property’s sale price up considerably, even though the physical construction material cost may be much lower.
The reverse can cause trouble, too. Construction costs can rise, and an old valuation may no longer reflect what it would cost to rebuild after a major loss.
For that reason, owner corporations should review the property’s replacement value periodically. Regular building valuations can help confirm that the insured amount still reflects current rebuilding costs. An outdated valuation can leave a scheme underinsured when it needs the policy most.
What About Things Inside Your Lot?
The strata policy generally isn’t a replacement for contents insurance. Furniture, clothing, televisions, computers, and other personal possessions usually fall to the individual owner to insure.
Consider a pipe leak that damages a shared wall and also ruins a laptop inside an apartment. Different parts of the resulting loss may fall under different insurance arrangements. The strata policy may deal with insured building damage, while the owner needs appropriate cover for personal belongings. It’s worth checking the boundary between the two policies before an incident occurs.
Are There Other Risks to Consider?
A standard building policy may not answer every insurance need within a strata scheme. The right additions depend on the property. A building with lifts, shared machinery, extensive gardens, commercial premises, or other facilities may face risks that a small residential complex doesn’t.
Depending on the circumstances, an owners corporation may need to consider cover relating to machinery breakdown, common property contents, workers’ compensation where applicable, or liability connected with office bearers.
Mixed-use developments deserve particular attention. Shops, offices, and residential lots can bring different risks and insurance costs. Consumer Affairs Victoria notes that mixed-use developments may have higher insurance costs for some lots because of their use.
Check the Policy Before Renewal
Owners corporations should also ask how the premium was calculated and whether appropriate quotes have been obtained. A cheaper premium isn’t necessarily useful if the policy leaves important risks uncovered.
For owners, the practical question is simple: If something serious happened tomorrow, would we know what our insurance actually covers? Knowing the answer before a claim arises is far better than finding out afterwards. Strata insurance has several moving parts, but understanding the building cover, liability protection, personal contents, and local requirements gives owners a much clearer picture of what they need.
Source: https://images.pexels.com/photos/28463539/pexels-photo-28463539.jpeg